UAE E-Invoicing Threshold: Are You in the AED 50 Million Wave?
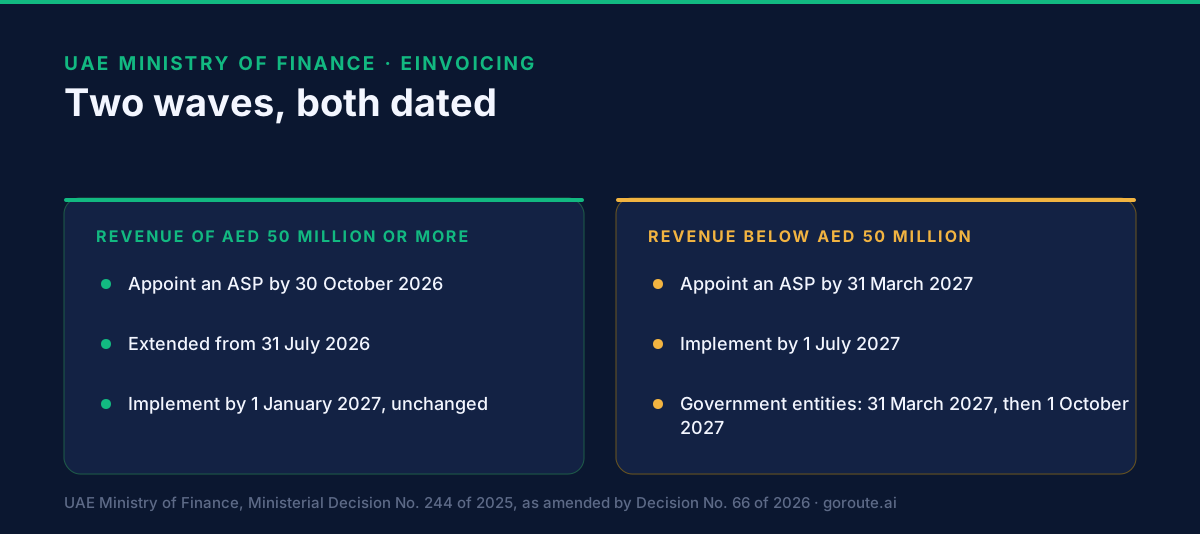
Revenue of AED 50 million or more: appoint a UAE e-invoicing provider by 30 October 2026, implement by 1 January 2027. Below it: 31 March and 1 July 2027.
Last updated .
The short answer
Two tests decide which UAE e-invoicing dates are yours: whether you are a person subject to the UAE's eInvoicing system, and whether your revenue is equal to or exceeds AED 50 million. If both are true, Ministerial Decision No. 244 of 2025, as amended, sets 30 October 2026 as your date to appoint an Accredited Service Provider and 1 January 2027 as your date to implement e-invoicing. If your revenue is below the threshold, the same decision gives you later dates: appoint by 31 March 2027 and implement by 1 July 2027. If you are in the first group and have not yet appointed a provider, the obligation does not lapse and the implementation date has not moved; our UAE e-invoicing page sets out what the Ministry's texts say to do next.
| Who | Appoint an Accredited Service Provider by | Implement by |
|---|---|---|
| Revenue of AED 50 million or more | 30 October 2026 (extended from 31 July 2026) | 1 January 2027 |
| Revenue below AED 50 million | 31 March 2027 | 1 July 2027 |
| Government entities | 31 March 2027 | 1 October 2027 |
All three rows are Article 5(1) of Ministerial Decision No. 244 of 2025. The first row's appointment date was moved by Ministerial Decision No. 66 of 2026, which changed nothing else. The full account of the first deadline is in our guide to who must appoint an ASP by 30 October 2026.
One group sits outside all three rows. Business-to-consumer transactions are not subject to the system until the Minister decides otherwise, and a business that makes only such sales is not subject to it (Article 5(2)).
Why the threshold matters more than the date
A date without its threshold turns a targeted obligation into a national one. That is not a pedantic distinction: it decides which of two timetables a finance team is working to, and the two appointment dates are five months apart.
The Ministry's dates travel far better than the sentence that qualifies them. "30 October 2026" fits in a headline, a slide and a supplier email; "for persons subject to the eInvoicing system whose revenue is equal to or exceeds AED 50 million" does not. So the date arrives everywhere and the threshold arrives sometimes. Businesses well below the line end up planning against a deadline that was never theirs, while businesses above it hear a general announcement and assume it is somebody else's project.
The first two dates carry the same threshold. The appointment deadline of 30 October 2026 and implementation on 1 January 2027 apply to the same population. Below the line, the same decision sets 31 March 2027 and 1 July 2027. None of these is a general UAE e-invoicing date on its own.
What counts as revenue for the AED 50 million test?
Gross income, from your financial statements. Article 1 of Decision No. 244 defines revenue as "the gross income earned by a Person during the most recent Accounting Period, based on the financial statements prepared in accordance with applicable legislation in the State or, if such financial statements are not available, based on other documentation acceptable to the Authority." The Authority is the Federal Tax Authority.
Three things follow from that wording.
- It is not taxable supplies. Taxable supplies is a VAT concept with its own inclusions and exclusions. The decision's test is gross income from the accounts. A business with substantial zero-rated or out-of-scope activity can be above one line and below the other, and the decision uses the accounting figure.
- It looks at the most recent accounting period. The figure is read from the latest financial statements, not an average and not a forecast, for an established business.
- A newly established company is a special case. The Ministry's October 2026 programme briefing notes that for a newly established company the test is based on the projected revenue for the ongoing financial year.
What we cannot point you at is a published Ministry clarification for the harder edge cases, such as an accounting period shorter than a year or restated accounts. If your number is anywhere near AED 50 million, take the question to whoever advises you on tax, and write down the answer and who gave it.
Is the AED 50 million test on group revenue or entity revenue?
This is the question we are asked most, and the decision text settles it, not an article. The threshold attaches to a person subject to the eInvoicing system, and the revenue is that person's gross income from its financial statements. So the real question for a group is which of your entities is such a person in its own right, and what that entity's statements show.
Two practical notes that are safe to give:
- Answer this first, before anything else. Scope decides whether your appointment date is 30 October 2026 or 31 March 2027, and getting it wrong in either direction is expensive.
- Write down the answer and who gave it. In twelve months somebody will ask why the group concluded what it concluded, and "we thought so at the time" is a poor record.
What if our revenue is just below AED 50 million?
Then your dates are 31 March 2027 to appoint a provider and 1 July 2027 to implement, under Article 5(1)(b) of Decision No. 244. The 2026 extension did not touch them.
If your revenue sits near the line, the useful question is not "what is the date for us" but "which side of the test are we on, and who decides that". That is the definition in the section above, applied to your latest financial statements. Because the test reads the most recent accounting period, a business just below the line this year is worth re-checking when the next statements are signed.
An earlier version of this page said no date had been published for businesses below the threshold. That was wrong: Article 5(1)(b) and (c) have set these dates since Decision No. 244 was issued.
What has to happen by 30 October 2026 if you are in scope?
One thing: an Accredited Service Provider has to be appointed. That is what the 30 October 2026 date requires. Being able to issue compliant invoices is the 1 January 2027 outcome, and it is the longer piece of work.
In practice the appointment is a shortlist, a due-diligence pass that finance and IT both sign off, a contract, and then an integration. The contract meets the appointment date; the integration meets the implementation date. Treating them as a single task is the commonest way a project that started early still finishes late. The appointment deadline moved outward while implementation did not, so the gap between them is shorter than it was.
If 30 October 2026 has passed and you are in scope without a provider, the obligation still stands and the implementation date has not moved; the UAE e-invoicing page sets out what the Ministry's texts say for that case. If you are already into the shortlist, how to choose an Accredited Service Provider covers where the official list is and what to ask each provider.
How many providers are there to choose from?
67 accredited, on the Ministry's published list read on 19 October 2026, with 3 more shown separately as pre-approved and still in final production assessment.
Date that figure whenever you use it, including when you read it here. It was 60 on 4 October 2026, and under half of today's figure at the Ministry's May 2026 announcement. An undated number goes stale without anyone noticing. The Ministry publishes the list of Accredited Service Providers itself, and that list, not a comparison article and not this page, is the authority on who is accredited today.
Three notes for a shortlist. Read the list on the day you shortlist, because a provider in final assessment last month may be accredited this month. A pre-approved provider is not yet accredited, so appointing one does not meet the obligation to appoint an Accredited Service Provider. And check the exact name on the list against the exact legal entity you would be contracting with: groups trade under several names, and the accredited one is the name the Ministry published.
If you are not in the first wave, what should you do now?
Nothing on this page is a compliance opinion about your business. If you are below the threshold, your obligation is dated: appoint a provider by 31 March 2027 and implement by 1 July 2027. The work that serves that date is the same work the first wave is doing, and starting it early costs little.
- Find out what actually issues your invoices today. In most organisations it is more than one thing: an ERP, a billing system, a point-of-sale estate, and a spreadsheet somebody maintains. The last one usually causes the trouble.
- Ask your largest customers what they will need from you. Businesses in the first wave change how they receive invoices from 1 January 2027, and that lands on their suppliers whichever row the supplier sits in.
- Shortlist from the Ministry's list well before 31 March 2027. The appointment is a procurement, and procurements take longer than their deadlines suggest.
- Keep the scope answer current. Revenue moves. A business below the threshold on one set of financial statements may not be on the next, and the test is worth re-running rather than remembered.
Three ways this threshold gets misread
Each can be checked against the Ministry's own text, which is why they are worth naming.
"The UAE e-invoicing deadline is 30 October 2026." Only for businesses at or above the AED 50 million revenue threshold. Stated bare, a targeted obligation becomes a national one.
"We are under the threshold, so there is no date for us." There is: 31 March 2027 to appoint, and 1 July 2027 to implement. Government entities have 31 March 2027 and 1 October 2027.
"It has all been pushed back." The appointment deadline for the first wave moved from 31 July 2026 to 30 October 2026. Implementation remains 1 January 2027, and the dates for everyone else did not move. Reading the first change as though it moved everything is how an organisation quietly loses integration time.
Where do these rules come from?
From the Ministry of Finance's own decisions and announcement, linked so you can read them rather than take our word for it:
- Ministerial Decision No. 244 of 2025 on the implementation of the electronic invoicing system: the definition of revenue (Article 1) and the dates for every group (Article 5).
- Ministerial Decision No. 66 of 2026, the instrument that moved the first wave's appointment deadline.
- The Ministry's announcement of targeted amendments to the eInvoicing system decisions, which is where the extension and the unchanged implementation timeline are stated.
- The Ministry's list of Accredited Service Providers.
If a page gives you a UAE e-invoicing date without linking the decision that sets it, that is a reason to check before acting on it.
Where GoRoute stands, plainly
GoRoute is not on the UAE Ministry of Finance's list of Accredited Service Providers. If you are appointing an ASP for the UAE, appoint one from that list.
What GoRoute is: an e-invoicing service provider accredited in Oman by the Oman Tax Authority, through Union Digital Technologies SPC, and a Peppol-certified Access Point (Service Provider ID POP000991, ClayDesk LLC). We publish this explainer because the same finance teams ask us the same scope question across the Gulf, and because the Ministry's decisions are easier to act on when somebody links them.
Next steps that may be more use than this page: the deadline guide for what the 30 October 2026 date requires, the GCC e-invoicing comparison if you operate in more than one Gulf market, the PINT AE readiness guide for how UAE invoices are exchanged, and the UAE e-invoicing page for the whole picture. You can also book a working session.
Sources
- Ministerial Decision No. 244 of 2025, Articles 1 and 5
- Ministerial Decision No. 66 of 2026
- UAE Ministry of Finance, announcement of targeted amendments to the eInvoicing system decisions
- UAE Ministry of Finance, UAE eInvoicing Programme briefing, October 2026
- UAE Ministry of Finance, eInvoicing Accredited Service Providers — read on 19 October 2026: 67 accredited and 3 pre-approved
Each source above was re-read from the Ministry's site on 19 October 2026. That reading corrected the threshold to the decision's own wording ("equal to or exceeds"), added the decision's definition of revenue and the dates for businesses below the threshold, and replaced the May 2026 provider count with the count on the day. On 28 October 2026 the search title, description and opening answer were reworded so that they stay accurate once 30 October 2026 has passed; no date, threshold or source changed.
Frequently asked questions
- Does the UAE deadline of 30 October 2026 apply to my business?
- It applies if you are a person subject to the UAE eInvoicing system and your revenue is equal to or exceeds AED 50 million. Both parts have to be true. If your revenue is below that line, your dates are 31 March 2027 to appoint an Accredited Service Provider and 1 July 2027 to implement.
- What is the UAE e-invoicing revenue threshold?
- AED 50 million. Ministerial Decision No. 244 of 2025 applies the first dates to a person whose revenue is equal to or exceeds AED 50,000,000, and defines revenue as the gross income earned in the most recent accounting period, based on the financial statements. At or above the line: appoint an Accredited Service Provider by 30 October 2026 and implement by 1 January 2027. Below it: 31 March 2027 and 1 July 2027.
- Is the AED 50 million test based on group revenue or entity revenue?
- The test attaches to a person subject to the eInvoicing system, so for a group the question is which of its entities is such a person in its own right, and what that entity's financial statements show. Take that question to the decision and to whoever advises you on tax before assuming the answer.
- What happens if our revenue is below AED 50 million?
- You have your own dates, in the same decision. Under Article 5(1)(b) of Ministerial Decision No. 244 of 2025, you appoint an Accredited Service Provider by 31 March 2027 and implement e-invoicing by 1 July 2027. The 2026 extension changed only the dates for the AED 50 million group.
- Was the UAE appointment deadline always 30 October 2026?
- No. It was 31 July 2026 and the Ministry of Finance extended it to 30 October 2026. Cite the old date only as the one that was extended. Mandatory implementation was not moved by that extension and remains 1 January 2027.
- Is GoRoute an Accredited Service Provider in the UAE?
- No. GoRoute is not on the UAE Ministry of Finance's list of Accredited Service Providers. GoRoute is accredited in Oman by the Oman Tax Authority, through Union Digital Technologies SPC, and is a Peppol-certified Access Point.
About Dr. Syed Raza
Dr. Syed Raza is an IT Enterprise Architect at ClayDesk LLC and leads the GoRoute platform. He works across Peppol Access Point and SMP infrastructure, PINT jurisdictions (Oman, AU/NZ, EU, JP, MY, SG), and national CTC regimes, translating regulatory detail into production-grade e-invoicing systems.
Building on Peppol?
GoRoute is a certified Peppol Access Point & SMP. Book a demo or read the docs to get started.