Oman E-Invoicing Threshold: Are You in the April or October 2027 Wave?
Oman's e-invoicing threshold is OMR 5,000,000 of annual supplies. Above it you start 1 April 2027, at or below 1 October 2027. Plus what is left undefined.
Last updated .
The short answer
OMR 5,000,000 of annual supplies. Above it, you are in the first wave and must issue electronic tax invoices from 1 April 2027. At or below it, 1 October 2027.
| Your annual supplies | Your date | Runway from 29 October 2026 |
|---|---|---|
| Above OMR 5,000,000 | 1 April 2027 | about 5 months |
| OMR 5,000,000 or below | 1 October 2027 | about 11 months |
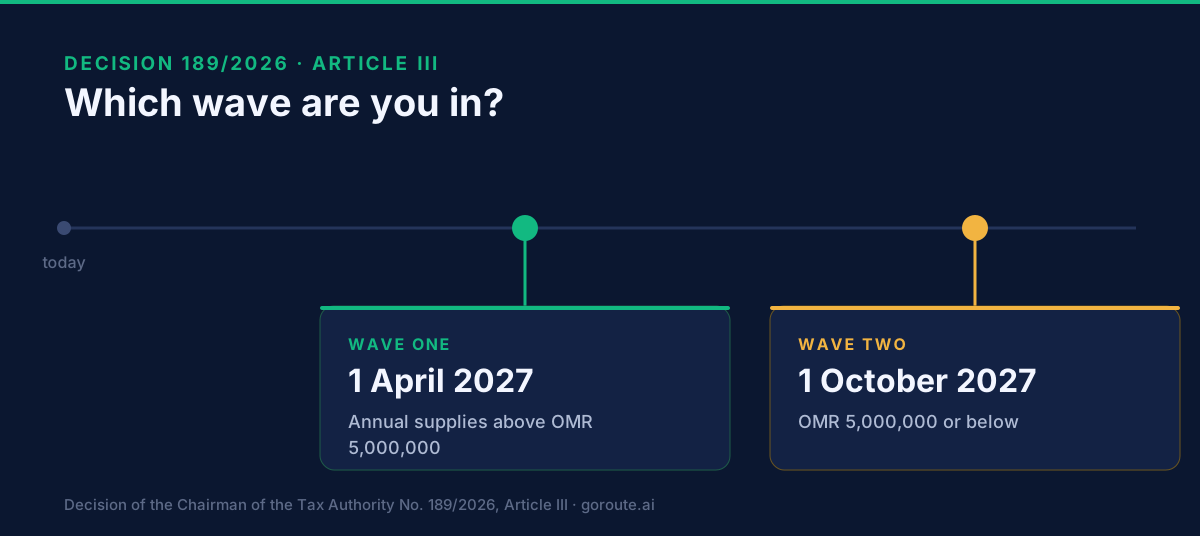
Both dates come from Article III of Decision 189/2026, the Chairman's decision amending the VAT Executive Regulations. The law sets two dates. The Tax Authority's FAQ still says small and medium businesses are included "within the third phase of the project", but it no longer lists the phases. On the law, a business at or under OMR 5,000,000 is on 1 October 2027, and every VAT-registered taxpayer is in one of these two groups. Whether small businesses must e-invoice, and how to do it with the software they have, is on Do small businesses in Oman have to e-invoice? Optional early adoption, which the FAQ allows, is on starting e-invoicing in Oman before your 2027 date. How the Tax Authority says the supplies are counted, and over which months, is set out below.
What "annual supplies" actually means
The decision uses the phrase annual supplies value. Three things follow from that wording.
It is a supplies test, not a profit test. A business with thin margins on high volume can be in the first wave while a smaller, more profitable one is in the second. If you are reasoning from your bottom line, you are reasoning from the wrong number.
It tracks what you already report. For most VAT-registered businesses the closest existing figure is the output value on your VAT returns. That is the number to start from.
It is stated without qualification — which brings us to the part most coverage is skipping.
How does the Tax Authority count annual supplies?
Over two twelve-month periods, and either one is enough to put you in the April wave. The decision itself sets no reference period. On 28 October 2026 the Tax Authority rewrote its Fawtara FAQ and answered the question there, in a new entry headed "How should I determine whether I am required to implement e-invoicing from 1 April 2027?".
The two tests. You must issue electronic tax invoices from 1 April 2027 if either:
- your supplies from April 2026 to 31 March 2027 exceed OMR 5,000,000, or
- the supplies you expect from 1 April 2027 to 31 March 2028 exceed OMR 5,000,000.
If neither is met, your date is 1 October 2027. The FAQ calls the total value of annual supplies "as of 31 March 2027" the key reference.
What goes into the total. The FAQ lists three things to include:
| Include | As the FAQ puts it |
|---|---|
| Taxable supplies | "The value of your taxable supplies, excluding supplies of capital assets" |
| Reverse-charge supplies | "The value of goods and services subject to the Reverse Charge Mechanism" |
| Intra-GCC supplies | "The value of your intra-GCC supplies of goods and services" |
So selling a capital asset, such as premises you trade from, does not push you over the line, while reverse-charge and intra-GCC amounts count towards it.
Who the rule covers. The same test applies to resident and non-resident taxpayers. A non-resident counts only the supplies it makes in Oman, and a VAT group is assessed as one group rather than member by member. Both cases, and what each group member still has to set up with a provider, are on Oman e-invoicing for VAT groups and non-residents.
What the FAQ settles, and what it leaves open
It settles four things the decision left open when this article was first written:
- The reference period, which is the year to 31 March 2027, or the year that follows it.
- A business that is growing. The forward test catches it. If you expect to pass OMR 5,000,000 in the year from 1 April 2027, you are in the April wave even if you were below it last year. Worked examples are here.
- A new business. On the FAQ's wording, a business with no trading history is judged on the forward test, since that test asks only what you expect to supply. The guide for a new or growing business walks through it.
- Capital assets. They are out.
It leaves two things open:
- Zero-rated and exempt supplies. The FAQ does not name either. If a large part of your turnover is zero-rated exports or exempt supplies, and you are close to the line, ask the Authority in writing how to treat them.
- How "expected" supplies are evidenced. The FAQ gives no method. A budget or forecast your board has approved is the natural starting point, but that is our reading, not the Authority's.
The FAQ is the Authority's guidance. Decision 189/2026 is the law that sets the two dates, and its wording, "annual supplies value", has not changed.
The rule of thumb if you are close
Plan for April.
The asymmetry decides it. Preparing six months early costs you readiness you were going to need anyway. Preparing six months late means missing a statutory deadline, with the invoices you cannot legally issue sitting between you and getting paid.
The same logic applies to the forward test. If your forecast for the year from 1 April 2027 is anywhere near OMR 5,000,000, take the earlier date.
What being in a wave actually obliges you to do
The date is when you must issue tax invoices in an approved and secured electronic format, with integrity, retention and a unique number for each invoice. That obligation covers more transactions than most finance teams expect:
- supplies to non-taxable persons — so B2C is in scope, and simplified invoices run on the same clock
- deemed supplies, which often have no invoice at all in a paper process
- consideration received before the date of supply — deposits and prepayments, which is the trigger most ERPs miss
There is also an obligation on your systems rather than your documents: Article 143 bis 1 requires security, continuity and data recovery measures that sit with the taxpayer regardless of who runs the platform.
Can you be exempted?
Yes, narrowly. Article 143 bis 2 allows the Chairman, on a request with supporting documents and acceptable reasons, to grant exemption from issuing the electronic tax invoice for a period the Authority determines — conditional on filing returns within the legal deadlines in the prescribed format, and paying tax due on time.
It is discretionary, time-limited, and available only to taxpayers whose compliance record is already clean. It exists for genuine hardship. It is not a route around a wave, and building a plan on it would be unwise.
What to do now
- Work out both totals the FAQ asks for: your supplies from April 2026 to 31 March 2027, and your forecast for 1 April 2027 to 31 March 2028. Leave out capital assets; include reverse-charge and intra-GCC supplies.
- If either is within about 15% of OMR 5m, plan for April 2027, and if zero-rated or exempt supplies could tip the result, write to the Authority about them.
- Count your invoice-issuing systems — ERP, POS, billing platform, and the spreadsheet in a branch office. All of them are in scope, including Excel and TallyPrime.
- Check your numbering — one unique number per invoice, across every issuing point.
- Test in a sandbox before the queue forms. Testing is free now; capacity in late 2026 will not be.
If you are part of a VAT group or a foreign business registered in Oman, read how the test applies to VAT groups and non-residents next. If you are a small or new business, read whether small businesses in Oman have to e-invoice or which date applies to a new or growing business. If you want to start before your date, see starting e-invoicing in Oman early.
The Oman compliance page sets out the full requirements, the Peppol API shows the integration, the tutorials and developer documentation show what the build involves, and you can book a working session with our Oman team. If you invoice across the Gulf, the picture is moving in Saudi Arabia, Qatar and the UAE at the same time.
Sources
- Decision of the Chairman of the Tax Authority No. 189/2026, Article III
- Oman Tax Authority, Fawtara FAQs, question 5, page stamped "Last updated: 28 October 2026", read 29 October 2026
- Oman Tax Authority and the Fawtara portal
Frequently asked questions
- What is the Oman e-invoicing threshold?
- OMR 5,000,000 of annual supplies. Taxpayers above it must issue electronic tax invoices from 1 April 2027; taxpayers at or below it from 1 October 2027. Both dates come from Article III of Decision 189/2026.
- Is the threshold based on profit or turnover?
- Neither exactly. The decision expresses it as the value of annual supplies, which is closer to the output value you already report on VAT returns than to profit. It is a supplies test, not an income test.
- Does the threshold include zero-rated and exempt supplies?
- The Tax Authority's Fawtara FAQ, rewritten on 28 October 2026, lists what to count: taxable supplies excluding capital assets, goods and services under the reverse charge, and intra-GCC supplies of goods and services. It does not name zero-rated or exempt supplies. If either is a large part of your turnover and you are near OMR 5,000,000, confirm the treatment with the Authority in writing.
- Which twelve months are measured?
- Two periods, and meeting either one is enough. The Tax Authority's FAQ puts you in the 1 April 2027 wave if your supplies from April 2026 to 31 March 2027 exceed OMR 5,000,000, or if the supplies you expect from 1 April 2027 to 31 March 2028 exceed it. If neither is met, your date is 1 October 2027. Decision 189/2026 itself sets no period; the FAQ is where the Authority answered it.
- What happens if I am just below OMR 5 million?
- Plan for April 2027. The consequence of being wrong in that direction is six months of unnecessary readiness; the consequence of being wrong the other way is missing a statutory deadline.
- Can a business be exempted from the threshold?
- Article 143 bis 2 lets the Chairman grant a time-limited exemption on request with supporting documents and acceptable reasons, conditional on filing returns and paying tax on time. It is discretionary relief for hardship, not a way to opt out of a wave.
About Dr. Syed Raza
Dr. Syed Raza is an IT Enterprise Architect at ClayDesk LLC and leads the GoRoute platform. He works across Peppol Access Point and SMP infrastructure, PINT jurisdictions (Oman, AU/NZ, EU, JP, MY, SG), and national CTC regimes, translating regulatory detail into production-grade e-invoicing systems.
Building on Peppol?
GoRoute is a certified Peppol Access Point & SMP. Book a demo or read the docs to get started.