IRAS InvoiceNow: How Invoice Data Reaches IRAS, and When It Applies to You
IRAS InvoiceNow explained: what the GST InvoiceNow Requirement is, who sends invoice data to IRAS, what travels, and your 2028 to 2031 date by turnover.
Last updated .
IRAS InvoiceNow is Singapore's GST reporting duty carried over the Peppol network: every GST-registered business will send invoice data to IRAS through InvoiceNow, in phases that end on 1 April 2031. Your invoice still travels to your customer over Peppol. A copy of the invoice data goes to IRAS from your access point, not from you, and there is no portal to log into. This page covers what IRAS requires, who sends what, and when it applies to you, with every date taken from IRAS's own pages as read on 20 October 2026.
If you want the network rather than the tax duty, the Singapore InvoiceNow guide explains what InvoiceNow is and IMDA's role. This page is the IRAS side only.
What is the GST InvoiceNow Requirement?
The GST InvoiceNow Requirement is IRAS's rule that GST-registered businesses must submit invoice data to IRAS using an InvoiceNow-Ready Solution. An IMDA-accredited access point transmits the data through a government API. It covers sales and purchases, is mandatory, and is phased in by cohort from 1 November 2025 to 1 April 2031.
IRAS's own wording is short: "All GST-registered businesses must submit invoice data to IRAS using InvoiceNow-Ready Solutions. This is mandatory and will be rolled out in phases." The detail sits in its e-Tax Guide, Adopting GST InvoiceNow Requirement for GST-registered Businesses (second edition, 9 March 2026), and in its FAQ (version of 23 September 2026). Both are linked under Sources.
How does invoice data reach IRAS?
Through five corners. The first four are ordinary Peppol; the fifth is what Singapore's GST requirement adds.
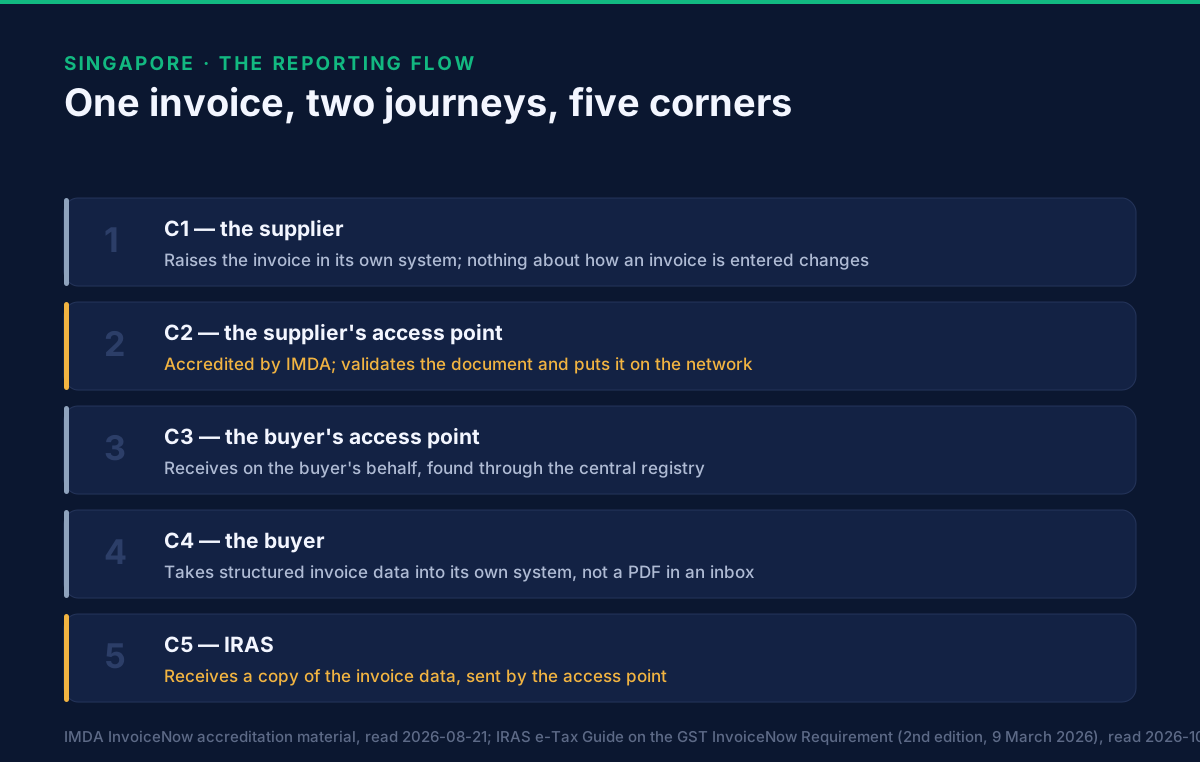
| Corner | Who | What happens |
|---|---|---|
| C1 | Supplier | Raises the invoice in its own accounting system |
| C2 | Supplier's access point | Validates against Singapore's billing profile and puts the document on the network |
| C3 | Buyer's access point | Receives on the buyer's behalf, discovered through the SG Peppol Directory |
| C4 | Buyer | Takes structured invoice data into its own system |
| C5 | IRAS | Receives a copy of the invoice data, transmitted through the government API |
The four-corner part is the Peppol model that runs in more than forty countries. Corner five is a Singapore addition, and in IMDA's accreditation material it is named exactly that: the C5 leg, tested separately from ordinary network delivery before a provider is allowed to operate it.
The order matters. IRAS's e-Tax Guide says the copy goes to IRAS "once the invoice data is successfully sent to the customer's Access Point". The buyer's delivery comes first, and the report follows it.
Who actually sends the data?
Your access point does. In IRAS's words, once a business activates the feature to submit invoice data, "IRAS receives a copy of the invoice data through IMDA-accredited Access Point Providers." The access point holds the connection to the government API, reached through Singapore's API exchange, APEX, and the accreditation that permits it to use it. From the business's side there is no second submission and no upload.
Two things do fall to you.
- Turning it on. IRAS's FAQ is explicit: if the GST InvoiceNow submission feature is not activated, your Peppol invoices "will continue as usual, but they would not be transmitted to IRAS". Being on InvoiceNow is not the same as reporting through it.
- The data itself. A missing GST category, a customer without a UEN, or a foreign-currency invoice with no Singapore-dollar tax amount will stop a document before anything correct reaches IRAS. Those checks belong to your ERP, and they are set out in what an InvoiceNow-ready ERP is.
If you run an off-the-shelf package, IRAS's route is to check that it is on IMDA's list of accredited InvoiceNow-Ready Solutions. If you run your own enterprise system, IRAS's route is to contact an IMDA-accredited access point provider and connect your system through it. IRAS says onboarding "may take as little as 3 months", and that most businesses finish within a year.
What actually travels to IRAS?
It depends on whether the transaction went over InvoiceNow. IRAS's e-Tax Guide sets out four submission types.
| Type | Transaction | What IRAS receives | When |
|---|---|---|---|
| 1A | A sale made over InvoiceNow | A copy of the Peppol invoice data, sent automatically | Generally real time or near real time |
| 1B | The matching purchase, received over InvoiceNow | The purchase as the buyer recorded it, extracted from the buyer's solution | On a schedule set in the solution |
| 2 | A sale made outside InvoiceNow | Invoice data extracted from the seller's solution | On a schedule, for example daily or weekly |
| 3 | A purchase made outside InvoiceNow | Invoice data extracted from the buyer's solution | On a schedule, for example daily or weekly |
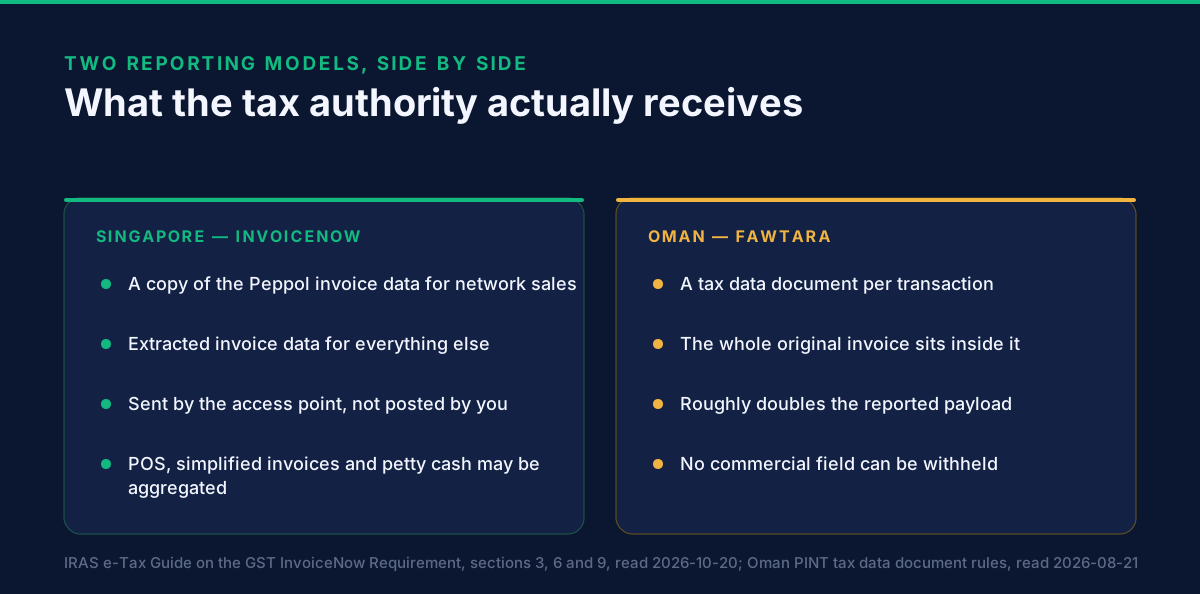
Type 1B is the one most often missed. When the buyer accepts a Peppol invoice, it records the GST category, the taxable amount and the input tax it intends to claim. That recorded version is what goes to IRAS from the buyer's side. So when both sides are in scope, one transaction on the network is reported twice: once as the seller's sale and once as the buyer's purchase.
Every submission carries IRAS's mandatory data elements. The e-Tax Guide lists them in section 9, and says the requirement has the force of law. They follow the content a GST tax invoice already needs under the GST (General) Regulations. In outline they are:
- Supplier details: Peppol endpoint ID, name, address and GST registration number
- Customer details: Peppol endpoint ID, name, address and identifier
- Invoice details: invoice number, line items, the GST category on each line, and the amounts and GST totals
The full specification is the Invoice Data Submission API Interface Specs on the APEX portal, which your provider works from. For the authoritative list, read section 9 of the e-Tax Guide rather than a summary of it, including this one.
Aggregation is allowed in three places. Supplies from point-of-sale systems, supplies covered by simplified tax invoices, and petty cash purchases may be sent as aggregated data rather than invoice by invoice.
How does that compare with Oman?
If you work across both markets, the contrast is worth knowing. Oman's report to the Tax Authority carries the complete original invoice embedded inside a tax data document, one per in-scope transaction. Singapore's network sales also send the invoice data, but off-network trade goes as extracted data, and three kinds of small-ticket trade may be aggregated. Oman's five-corner model sets out the other side: the same corner count, with a different fifth corner.
What about sales that never travel over the network?
They are reported too. IRAS's FAQ deals with a business whose customers are "mostly not onboard InvoiceNow". Its answer is that sales invoices issued outside the network are submitted as solution-extracted invoices, which is a Type 2 submission. If the business uses an InvoiceNow-Ready Solution, the data "is automatically extracted and transmitted to IRAS on a periodic basis".
The same applies to purchases. A paper or PDF invoice from a supplier not on InvoiceNow is recorded in your solution and sent as a Type 3 submission.
Two practical rules from IRAS's FAQ affect your customer master data:
- Customer details are mandatory, even for customers not on InvoiceNow. That means name, UEN and address, including for overseas customers, who are given their overseas registration number in the UEN field.
- Individuals are the exception. For customers who are non-GST-registered individuals, you may enter "NA" in the customer name and UEN fields.
Some transactions are out of scope. IRAS lists transactions that need not be sent:
- deemed supplies and goods exported without sales, where there is no underlying supply or purchase
- reverse charge transactions
- exempt financial services, and exchanges or loans of digital payment tokens
- import permits for importing goods
Is this a clearance model?
No, and the distinction matters when you are scoping.
- Clearance: the tax authority sits between supplier and buyer, and the invoice is not valid until it has been cleared. Delivery waits on the authority.
- Reporting alongside exchange: Singapore's shape. The commercial invoice goes to the buyer over Peppol, and the data goes to IRAS alongside it. Your customer is not waiting on a tax authority to receive their invoice.
IRAS's e-Tax Guide puts this in writing for outages. If the IRAS API is disrupted, businesses "can continue to transact with their customers and suppliers via the InvoiceNow network or outside the network as this process is independent from the submission to IRAS". The failed transactions are resubmitted once service is restored.
The practical consequence: a problem in the reporting leg is a compliance problem to fix, not an interruption to your customers' invoices.
When does this apply to my business?
It already applies to some businesses, and IRAS has now fixed the date for everyone else. These are the phases on IRAS's GST InvoiceNow Requirement page, read on 20 October 2026:
| From | Who it applies to |
|---|---|
| 1 November 2025 | Companies that register for GST voluntarily within 6 months of their incorporation date |
| 1 April 2026 | Businesses that apply for voluntary GST registration on or after 1 April 2026, whatever their incorporation date or business structure |
| 1 April 2028 | Businesses that apply for compulsory GST registration on or after 1 April 2028, and existing GST-registered businesses with total annual supplies up to S$200,000 |
| 1 April 2029 | Existing GST-registered businesses with total annual supplies up to S$1,000,000 |
| 1 April 2030 | Existing GST-registered businesses with total annual supplies up to S$4,000,000 |
| 1 April 2031 | Existing GST-registered businesses with total annual supplies above S$4,000,000 |
The smallest businesses go first. IRAS's FAQ explains why: smaller businesses mostly use off-the-shelf software that is already InvoiceNow-ready, while larger businesses need time to fit the change into their IT refresh cycles.
How do I find my own band?
- Look for IRAS's letter. IRAS says it has notified GST-registered businesses that were registered before 2026 of their mandatory implementation date. A business that did not receive one, for example because it has no GST returns for periods ending in 2025, will be told its date later.
- Or work it out. "Total annual supplies" means the standard-rated, zero-rated and exempt supplies in Box 4 of your GST returns, for every prescribed accounting period ending in calendar year 2025. If your quarters end in March, June, September and December, that is January to December 2025. If they end in January, April, July and October, it is November 2024 to October 2025. If they end in February, May, August and November, it is December 2024 to November 2025.
- Check it with IRAS's calculator. IRAS publishes a GST InvoiceNow implementation date calculator as a spreadsheet on the same page.
Nil returns count. A business that filed four GST returns showing S$0 in supplies is in the S$200,000 band and starts on 1 April 2028.
Two groups are exempt. IRAS excludes overseas entities, including overseas vendors registered under the Overseas Vendor Registration regimes. It also excludes businesses that must register for GST only because of the reverse charge regime.
Two readings of the timeline are wrong often enough to name. It is not "voluntary in Singapore"; that stopped being true on 1 November 2025. And 1 April 2026 was not a full business-to-business switch-on. It covered new voluntary GST registrants only.
Confirm your own start date against IRAS's GST InvoiceNow Requirement page. It is the only version that is authoritative on the day you read this.
When must the data reach IRAS?
By the earlier of two dates: the day you file the relevant GST return, or that return's filing due date. The relevant return is the one covering the period in which the transaction happened.
For a sale, the transaction date is the date the invoice was issued. For a purchase, it is either the supplier's invoice date or the date you posted it into your accounting system, depending on how you already claim input tax. Network sales under Type 1A are sent as they happen. Everything else can be batched, provided the batch lands before that date.
What usually goes wrong first
In our experience of Peppol markets with a reporting leg, the failures cluster upstream of the tax authority, not at it:
- The participant was never registered. IRAS's first step is a Peppol ID: your provider registers your business in the SG Peppol Directory with your UEN. In Singapore this is completed by the business authenticating itself, not by the provider alone, and an unfinished registration expires.
- The submission feature was never switched on. Invoices flow to customers, and nothing reaches IRAS.
- A customer has no UEN. Peppol scheme
0195routes on it, and IRAS treats it as a mandatory data element. - A line has no GST category, or the wrong one. Singapore's rules distinguish standard-rated, zero-rated, exempt, out of scope, not GST-registered, and taxable supplies where GST need not be charged.
- A foreign-currency invoice carries no Singapore-dollar tax amount, which Singapore's validation requires.
- There is no receiving path. Sending is scoped, receiving is forgotten. Then the first supplier invoice arrives with nowhere to land, and the Type 1B purchase report has nothing to report.
Every one of these is visible by validating a real document before you are in scope. That costs nothing and can be done today. The general failure patterns are in validation errors you can prevent.
What to do next
- Establish your date. Find IRAS's letter or use its calculator, then check it against the table above.
- Validate one real invoice against the Singapore profile and read what comes back. The developer sandbox does this without sending anything, and the API documentation shows the calls behind it.
- Ask your provider how it handles all four submission types, not only Type 1A, and what it does when a transmission to IRAS fails. A reporting leg with no retry story is a reporting leg you will be chasing.
- Check the receiving side, not just sending.
To scope it against your own system, book a working session. If you are still choosing who connects you, read how to choose an InvoiceNow solution provider in Singapore next. For the market view see Singapore e-invoicing; for a walkthrough of the platform, see the tutorials; and for how the same integration reaches other Peppol countries, see the multi-country API and the Peppol access point.
Where GoRoute stands
GoRoute operates a Peppol-certified Access Point and SMP (Service Provider ID POP000991, ClayDesk LLC). Singapore adds its own requirements on top of ordinary Peppol — accreditation by IMDA, registration in the central registry, and the reporting leg described above — and those are the questions to put to any provider in writing, ours included, before a contract is signed.
Sources
- IRAS — GST InvoiceNow Requirement — the phases, the turnover bands, exemptions, scope and due dates (page last updated 8 October 2026; read 20 October 2026)
- IRAS — e-Tax Guide: Adopting GST InvoiceNow Requirement for GST-registered Businesses — the four submission types, mandatory data elements and API disruption (second edition, 9 March 2026)
- IRAS — Frequently Asked Questions for GST InvoiceNow Requirement — calculating total annual supplies, the submission feature, customers not on InvoiceNow (version of 23 September 2026)
- IMDA — nationwide e-invoicing framework — InvoiceNow and IMDA's role as Singapore's Peppol Authority
- IMDA — InvoiceNow technical playbook — the technical requirements behind the reporting leg
- SG Peppol Guide — billing specification — the Singapore billing profile and its validation rules
- OpenPeppol — the network the exchange runs on
Frequently asked questions
- What is the GST InvoiceNow Requirement?
- It is IRAS's rule that GST-registered businesses must send invoice data to IRAS through InvoiceNow, Singapore's Peppol network, using an InvoiceNow-Ready Solution. The data is transmitted by an IMDA-accredited access point, not uploaded by the business. It is mandatory and phased in by cohort from 1 November 2025 to 1 April 2031.
- How does invoice data reach IRAS through InvoiceNow?
- The invoice travels from supplier to buyer over the Peppol network in the ordinary four-corner way. Once the buyer's access point has it, a copy of the invoice data goes to IRAS automatically through the government API. Sales and purchases outside the network are extracted from the business's accounting solution and sent on a schedule. The business does not upload anything to IRAS itself.
- Does IRAS receive the whole invoice?
- For a sale made over InvoiceNow, IRAS's e-Tax Guide says a copy of the Peppol invoice data is transmitted automatically. For everything else, the solution extracts the invoice data and sends it. Either way the data must carry IRAS's mandatory data elements, which have the force of law. Point-of-sale, simplified tax invoice and petty cash data may be sent in aggregate.
- Who transmits the data — me or my provider?
- Your provider. IRAS says it receives a copy of the invoice data through IMDA-accredited access point providers, once the business has activated the GST InvoiceNow submission feature in its solution. What falls to you is upstream: the invoice data has to exist in your system, correctly categorised for GST, or there is nothing correct to transmit.
- Do invoices that never travel over Peppol still have to be reported?
- Yes. IRAS calls these Type 2 submissions for sales and Type 3 submissions for purchases. A paper or PDF invoice to a customer who is not on InvoiceNow is recorded in your InvoiceNow-Ready Solution, and the extracted invoice data is sent to IRAS through your access point. For customers who are non-GST-registered individuals, IRAS allows NA in the customer name and UEN fields.
- When does the GST InvoiceNow Requirement apply to my business?
- It already applies to companies that register for GST voluntarily within six months of incorporation (from 1 November 2025) and to all new voluntary registrants (from 1 April 2026). Existing GST-registered businesses follow by total annual supplies: up to S$200,000 from 1 April 2028, up to S$1 million from 1 April 2029, up to S$4 million from 1 April 2030, and above S$4 million from 1 April 2031. New compulsory registrants join on 1 April 2028.
- How do I work out which turnover band my business is in?
- Add up the standard-rated, zero-rated and exempt supplies in Box 4 of your GST returns for every prescribed accounting period ending in calendar year 2025. If your quarters end in January, April, July and October, that means November 2024 to October 2025. Nil returns count, so a business with S$0 in supplies falls in the first band. IRAS also publishes an implementation date calculator.
- When must invoice data reach IRAS?
- By the earlier of the date you file the relevant GST return and that return's filing due date. The relevant return is the one covering the period in which the transaction occurs. Peppol sales are generally transmitted in real time or near real time; extracted sales and purchase data can be sent on a regular schedule set in your solution.
- What is the difference between InvoiceNow and the GST InvoiceNow Requirement?
- InvoiceNow is Singapore's e-invoicing network, introduced by IMDA in 2019 and built on Peppol. The GST InvoiceNow Requirement is IRAS's reporting duty carried over that network: in addition to sending your customer an invoice, invoice data is transmitted to the tax authority. One is infrastructure; the other is an obligation that uses it.
- Is Singapore's model the same as a clearance regime?
- No. In a clearance regime the tax authority stands between supplier and buyer and the invoice is not valid until it has been cleared. Singapore keeps the commercial exchange on the Peppol network and adds a reporting leg alongside it. IRAS says that if its API is disrupted, businesses can keep transacting and resubmit the data once service is restored.
- What usually goes wrong first?
- Data, not transmission. A participant that was never registered in the SG Peppol Directory, a submission feature that was never activated, a customer with no UEN, a missing GST category on a line, or an invoice in a foreign currency with no Singapore-dollar tax amount. Each of these fails before anything correct reaches IRAS, and each is visible by validating a real invoice today.
About Dr. Syed Raza
Dr. Syed Raza is an IT Enterprise Architect at ClayDesk LLC and leads the GoRoute platform. He works across Peppol Access Point and SMP infrastructure, PINT jurisdictions (Oman, AU/NZ, EU, JP, MY, SG), and national CTC regimes, translating regulatory detail into production-grade e-invoicing systems.
Building on Peppol?
GoRoute is a certified Peppol Access Point & SMP. Book a demo or read the docs to get started.